- Reduced price
Extra 2% OFF
Pay ₹915.00 online and save ₹19.00
Free shipping with prepaid payment
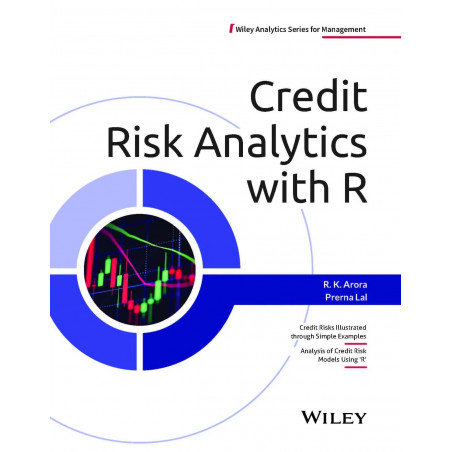
| Title | Credit Risk Analytics with R |
| Author | R. K. Arora, Prerna Lal |
| ISBN-13 | 9789357461559 |
| Publication | WILEY |
Credit risk analytics is a set of tools and techniques that enable lenders to take credit decisions and estimate the credit risk by predicting the credit behaviour of potential borrowers. Beginning with the fundamental concepts of credit risk analytics, this book offers in-depth insight into credit scoring models, probability of default (discrete time models and continuous time models) and modelling (exposures, recoveries, default correlations, and counterparty risk). Adopting a balanced strategy combining theoretical explanation and practical applications, the book demonstrates how you can build credit risk models using R and apply them into practice.
 General Enquiries: support@madrasshoppe.com |
Chat Support @ WhatApp 744 836 3000
 Free Shipping on prepaid orders above ₹999 ! | COD Available | Standard India Delivery: 4 - 7 Working Days
 Trusted by over 100,000 satisfied customers across India. 100% Secure Payments via Razorpay.
Credit risk analytics is a set of tools and techniques that enable lenders to take credit decisions and estimate the credit risk by predicting the credit behaviour of potential borrowers. Beginning with the fundamental concepts of credit risk analytics, this book offers in-depth insight into credit scoring models, probability of default (discrete time models and continuous time models) and modelling (exposures, recoveries, default correlations, and counterparty risk). Adopting a balanced strategy combining theoretical explanation and practical applications, the book demonstrates how you can build credit risk models using R and apply them into practice.
R. K. Arora, Prerna Lal is the author of Credit Risk Analytics with R.
Disclaimer:
| Title | Credit Risk Analytics with R |
| Author | R. K. Arora, Prerna Lal |
| ISBN-13 | 9789357461559 |
| Publication | WILEY |
Credit risk analytics is a set of tools and techniques that enable lenders to take credit decisions and estimate the credit risk by predicting the credit behaviour of potential borrowers. Beginning with the fundamental concepts of credit risk analytics, this book offers in-depth insight into credit scoring models, probability of default (discrete time models and continuous time models) and modelling (exposures, recoveries, default correlations, and counterparty risk). Adopting a balanced strategy combining theoretical explanation and practical applications, the book demonstrates how you can build credit risk models using R and apply them into practice.