- Reduced price
Extra 0% OFF
Pay ₹2,124.00 online and save ₹0.00
Free shipping with prepaid payment
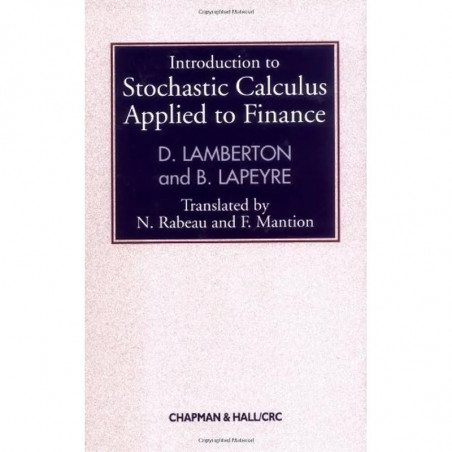
| Title | Introduction to Stochastic Calculus Applied to Finance, Second Edition |
| Author | Damien Lamberton, Bernard Lapeyre |
| ISBN-13 | 9780412718007 |
| Publication | CRC TBH |
In recent years the growing importance of derivative products financial markets has increased financial institutions' demands for mathematical skills. This book introduces the mathematical methods of financial modeling with clear explanations of the most useful models. Introduction to Stochastic Calculus begins with an elementary presentation of discrete models, including the Cox-Ross-Rubenstein model. This book will be valued by derivatives trading, marketing, and research divisions of investment banks and other institutions, and also by graduate students and research academics in applied probability and finance theory.
 General Enquiries: support@madrasshoppe.com |
Chat Support @ WhatApp 744 836 3000
 Free Shipping on prepaid orders above ₹999 ! | COD Available | Standard India Delivery: 4 - 7 Working Days
 Trusted by over 100,000 satisfied customers across India. 100% Secure Payments via Razorpay.
In recent years the growing importance of derivative products financial markets has increased financial institutions' demands for mathematical skills. This book introduces the mathematical methods of financial modeling with clear explanations of the most useful models. Introduction to Stochastic Calculus begins with an elementary presentation of discrete models, including the Cox-Ross-Rubenstein model. This book will be valued by derivatives trading, marketing, and research divisions of investment banks and other institutions, and also by graduate students and research academics in applied probability and finance theory.
Damien Lamberton, Bernard Lapeyre is the author of Introduction to Stochastic Calculus Applied to Finance, Second Edition.
Disclaimer:
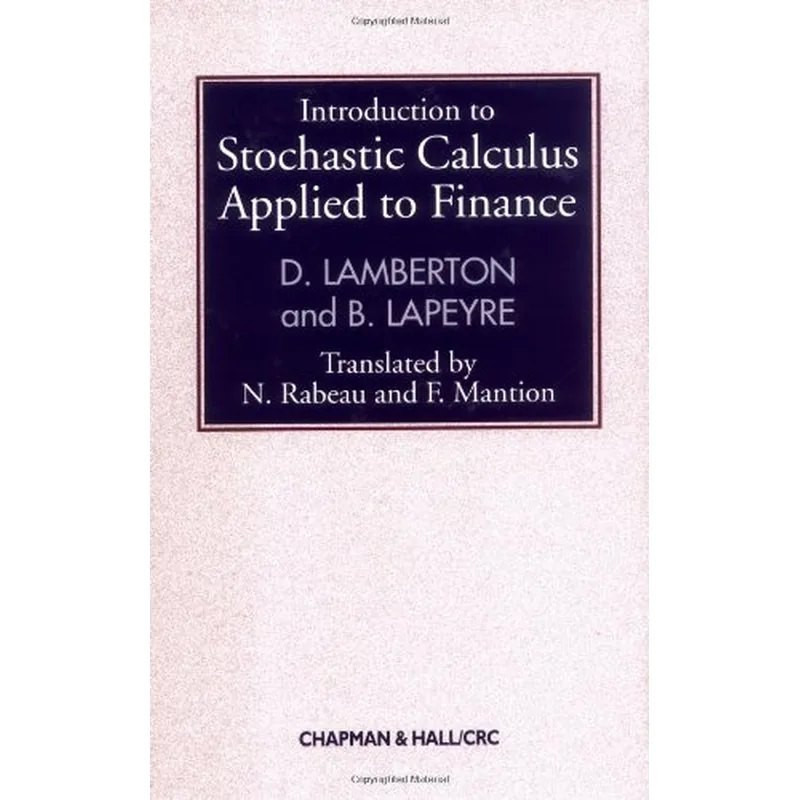
| Title | Introduction to Stochastic Calculus Applied to Finance, Second Edition |
| Author | Damien Lamberton, Bernard Lapeyre |
| ISBN-13 | 9780412718007 |
| Publication | CRC TBH |
In recent years the growing importance of derivative products financial markets has increased financial institutions' demands for mathematical skills. This book introduces the mathematical methods of financial modeling with clear explanations of the most useful models. Introduction to Stochastic Calculus begins with an elementary presentation of discrete models, including the Cox-Ross-Rubenstein model. This book will be valued by derivatives trading, marketing, and research divisions of investment banks and other institutions, and also by graduate students and research academics in applied probability and finance theory.